Articles
This is the full list of articles on ELTIF funds and real estate investing published on the portal. It brings together guides on how European long-term investment funds work, the changes introduced by ELTIF 2.0, liquidity and redemptions, fees, risks, fund documents and the main types of commercial real estate. Every article is based on the text of the relevant EU rules, lists its sources and shows the date of its next planned review. The articles are educational and independent. They do not recommend specific funds, providers or investment decisions, and they do not forecast returns. Start with the basics if you are new to the topic, or go straight to the question you need answered.
What is an ELTIF fund? A plain guide for investors
An ELTIF is a European fund label for long-term investment in real assets and unlisted businesses. It follows EU rules, must be run by an authorised AIFM, can be offered to retail investors after a suitability assessment, and is not a daily-liquid product.
ELTIF 2.0: what changed in the EU rules and why it matters
ELTIF 2.0 is Regulation (EU) 2023/606, which amended the ELTIF Regulation and applies from 10 January 2024. It widened eligible assets, raised borrowing limits, removed retail entry barriers and set conditions for redemptions during the life. The long-term, illiquid nature of ELTIFs did not change.
Types of investment funds compared: ELTIF, UCITS, ETF, AIF, property
A neutral comparison of ELTIFs, UCITS funds, ETFs, open-ended real-estate AIFs, funds for professional or qualified investors and direct property: how each is regulated, who it is for, how liquid it is, what it holds and what to watch out for.
ELTIF risks explained: what can go wrong and what to check
ELTIF investors can lose part or all of their capital, may be unable to sell when they wish, and depend on estimated valuations. Borrowing, concentration, costs, interest rates, tenants and currency add risks that vary by fund and are not removed by the ELTIF label.
Is an ELTIF liquid? Redemptions, lock-ups and exit options
An ELTIF is not a daily-liquid product. By default investors cannot request redemption before the end of the fund's life. Redemptions during the life are possible only if the rules allow them and strict conditions are met, and units can be transferred but not necessarily sold.
ELTIF fees explained: entry, ongoing, exit and performance
ELTIFs and similar funds can charge entry, ongoing, exit and performance fees, plus transaction and property-level costs. The KID, statute and prospectus show which apply, and small yearly differences compound into a large gap over a long holding period.
How does a real-estate fund work? Structure, income, exit
A real-estate fund pools investors' money so a manager can buy and run properties. Returns come from rent and changes in value, after costs and any borrowing. The unit value is an estimate from independent valuations, and exit depends on the fund's rules.
ELTIF for retail investors: rules, protections and steps
Since ELTIF 2.0, retail investors can buy ELTIFs without the former EUR 10,000 minimum and 10 % portfolio limit. The seller must carry out a MiFID II suitability assessment, give a suitability statement and a written alert on long life and matching. It suits only long-term investors.
What to check before investing in an ELTIF: 12-point checklist
Before investing in an ELTIF, read the KID, prospectus and statute, confirm the end date and redemption rules, check borrowing, concentration, costs and the manager, test your horizon and reserves, compare alternatives and consider independent advice.
Commercial real estate: how it earns income and what drives value
Commercial real estate is property used by businesses, such as offices, retail and warehouses. It earns income mainly from leases paid by business tenants, and its value depends on location, tenant quality, lease length and building condition. Funds hold it directly or via property companies.
Owning property directly or through a fund: how they compare
Direct ownership gives you control and a tangible asset but needs large capital, time and concentrated risk. A fund offers a share in a managed portfolio with less effort, but you give up control, pay fund costs and may face limited liquidity. Neither is better in general.
ELTIF documents: what to read before you invest
Before investing in an ELTIF, read the fund rules or statute, the prospectus, the KID, the latest annual report, your suitability statement and the written alert required for retail investors. Each document answers different questions, so read them together and ask the seller for anything missing.
ELTIF vs ETF: what is the difference and which fits you?
An ELTIF invests mainly in long-term real assets and by default has no redemption before the end of its life. An ETF typically tracks a liquid market and trades on an exchange. Neither is better in general: it depends on your goal, horizon and need for liquidity.
ELTIF vs UCITS mutual fund: key differences explained
An ELTIF is a long-term alternative investment fund under Regulation (EU) 2015/760 that holds mostly illiquid assets and restricts redemptions. A UCITS mutual fund under Directive 2009/65/EC invests mainly in liquid securities and allows regular redemption. Neither is better in general.
How to read a KID: risk indicator, costs and scenarios
The key information document is a short standardised sheet that explains what a product is, its risk indicator from 1 to 7, the recommended holding period, costs and illustrative scenarios. It helps you compare products, but it does not tell you everything about a fund.
How to verify an ELTIF is legitimate: provider and seller checks
Check that the manager is an authorised AIFM, that the fund appears in the ESMA register of ELTIFs, that a depositary is named and that the seller is an authorised investment firm. Pressure, unsolicited contact or promises of fixed returns are red flags.
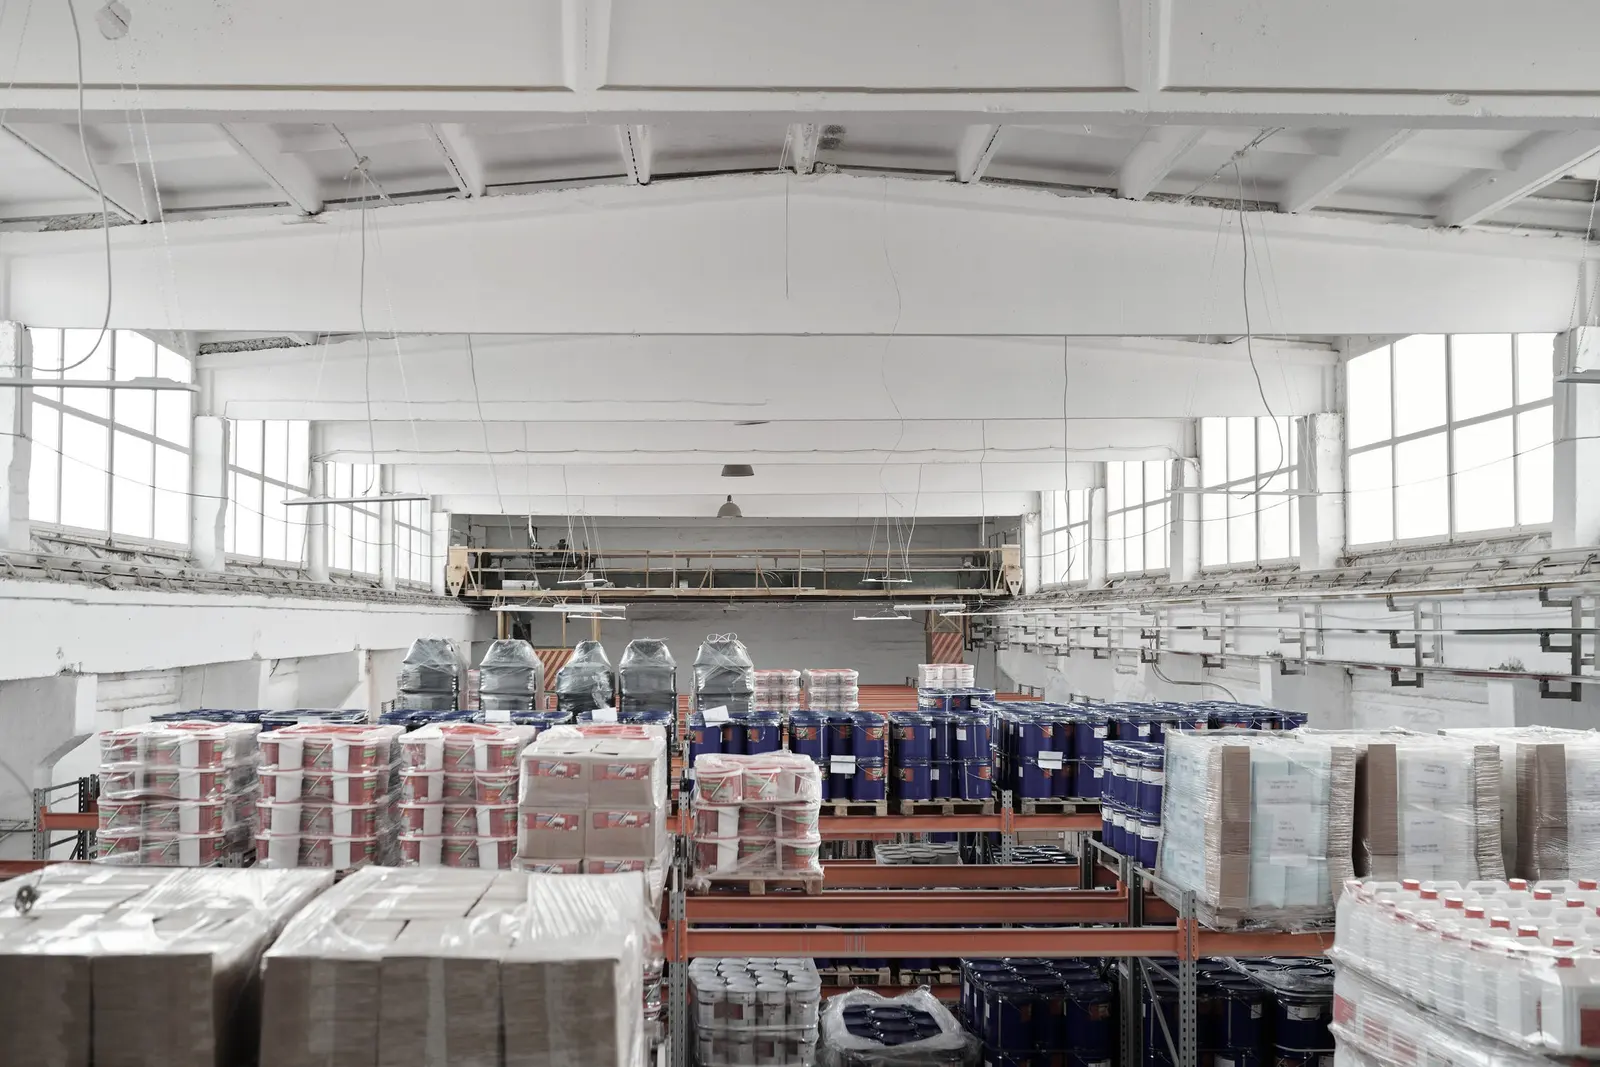
Logistics real estate: warehouses as an investment explained
Logistics real estate covers warehouses used to store and move goods, from large distribution centres to small last-mile units near cities. Income comes from leases with logistics operators and retailers. Value depends on location, transport links, building specification and tenant strength.
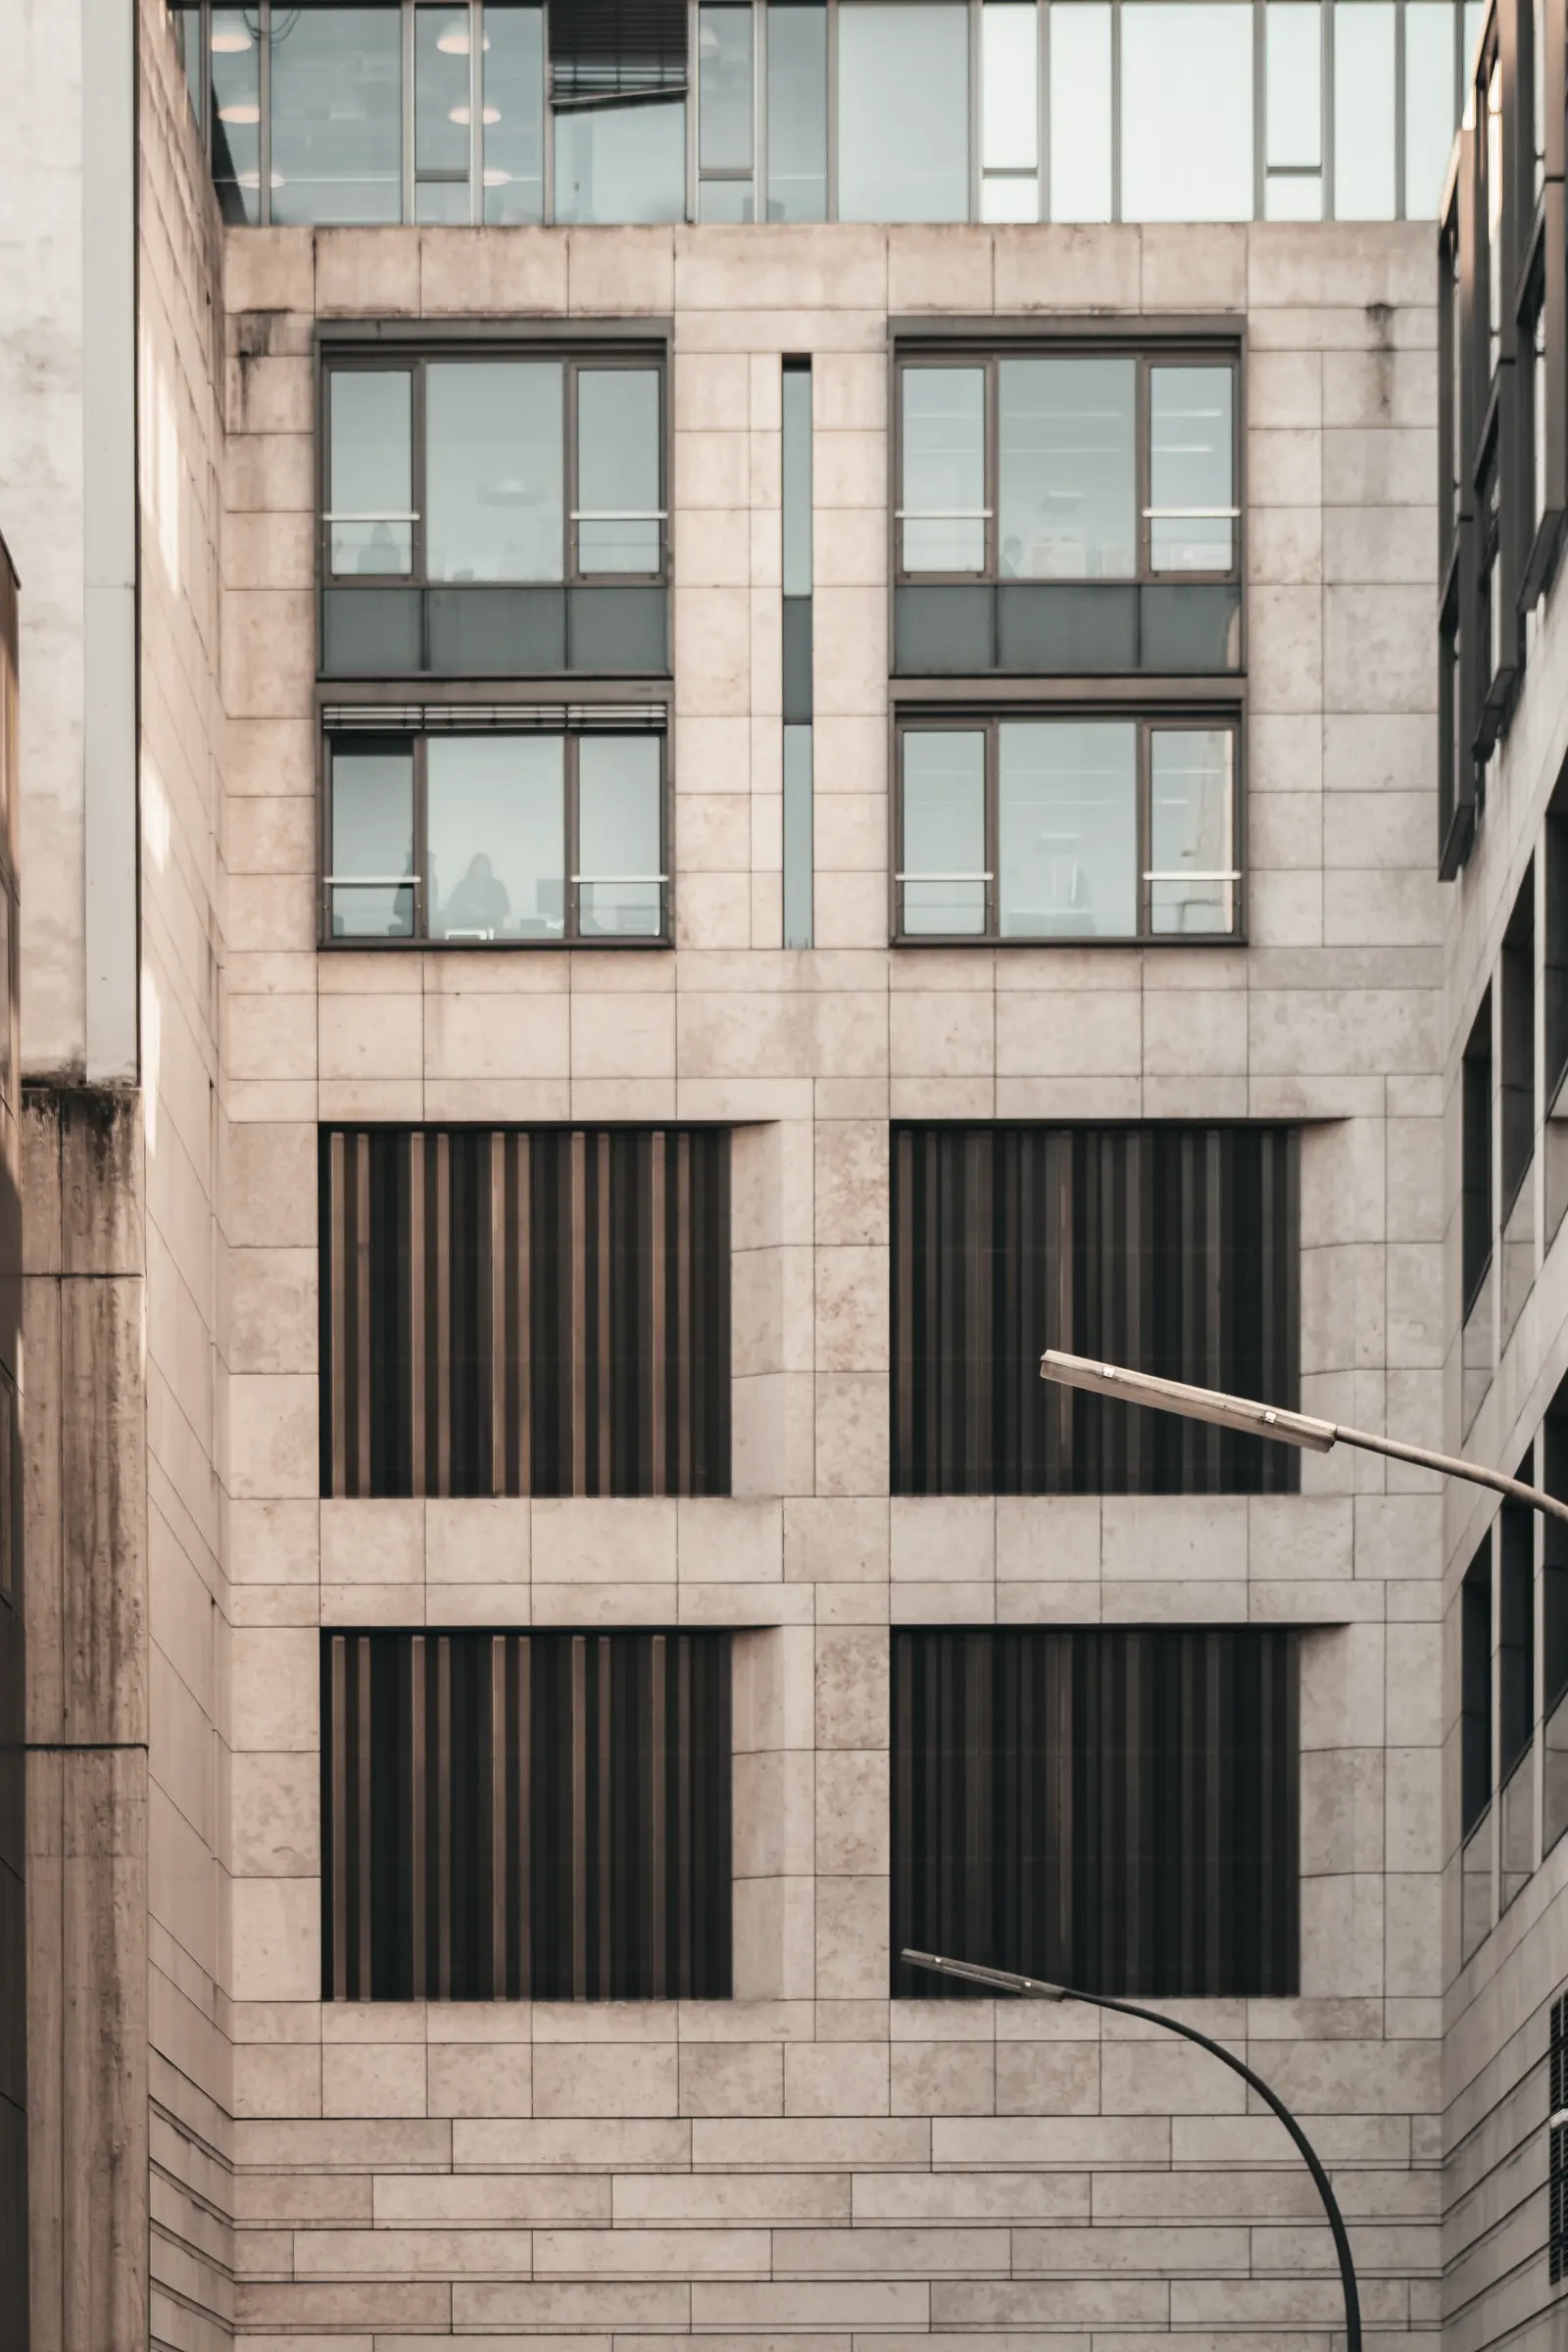
Office real estate: how office buildings work as an investment
Office real estate earns income from leases with companies and public bodies. Its value depends on location, building quality, lease length and tenant strength. Hybrid work, energy standards and the need for refurbishment are key qualitative factors, and vacancy is the main income risk.
Open-ended vs closed-ended funds: how they differ
An open-ended fund issues and redeems units on an ongoing basis at NAV. A closed-ended fund raises capital for a set period and does not redeem on demand, so investors exit at the end of its life or by selling to others. An ELTIF is closed-ended by default but may allow limited redemptions.
ELTIF 2.0 article by article: legal guide to Regulation 2023/606
Regulation (EU) 2023/606 amended the ELTIF Regulation from 10 January 2024. It widened eligible assets, lowered the eligible-asset floor to 55 %, moved borrowing to a NAV basis, created a professional-only regime, opened redemptions and matching, and grandfathered existing ELTIFs until 11 January 2029.
ELTIF borrowing and leverage limits under Article 16 explained
Under Article 16 of the ELTIF Regulation, an ELTIF that can be marketed to retail investors may borrow cash up to 50 % of NAV, and a professional-only ELTIF up to 100 % of NAV. Borrowing must serve investment or liquidity, match the asset currency or be hedged, and not outlast the fund.
ELTIFs in Luxembourg and Ireland: domicile, structures and tax
Of 327 ELTIFs in the ESMA register as of 31 August 2026, 176 are domiciled in Luxembourg, 87 in France and 35 in Ireland. Luxembourg offers several fund wrappers and exempts ELTIFs from subscription tax; Ireland has a dedicated ELTIF chapter in its AIF Rulebook and the ICAV structure.
ELTIF authorisation, marketing passport and retail suitability
An ELTIF must be authorised before it is marketed, and the authorisation is valid in all Member States. Marketing uses the AIFMD notification procedure for professional and retail investors. Retail sales require a MiFID II suitability assessment, a suitability statement and written alerts.
ELTIF master-feeder and fund of funds structures under ELTIF 2.0
ELTIF 2.0 allows an ELTIF to invest in other ELTIFs, EuVECAs, EuSEFs, UCITS and EU AIFs, and creates a formal master-feeder regime in which a feeder ELTIF invests at least 85 % of its assets in a master ELTIF, with look-through for the portfolio limits.
ELTIF matching mechanism: conditions under Article 19(2a) and the RTS
Article 19(2a) of the ELTIF Regulation lets fund rules provide for matching transfer requests of exiting investors with those of new investors during the life. It requires a written matching policy, fair and pro rata treatment and compatibility with liquidity management; the RTS adds pricing, timing and disclosure rules.
ELTIF portfolio composition: eligible assets, QPUs, limits, ramp-up
An ELTIF must invest at least 55 % of capital in eligible investment assets under Articles 10 and 11. Retail-eligible ELTIFs face 20 % single-asset limits and concentration caps; professional-only ELTIFs are exempt from most. The rules apply from a ramp-up date of at most five years or half the life.
ELTIF prospectus, PRIIPs KID and periodic reporting obligations
An ELTIF needs a published prospectus before any marketing and a PRIIPs key information document before marketing to retail investors. The prospectus has ELTIF-specific contents and cost disclosure, and the annual report adds items to the AIFMD annual report, due within six months of year end.
ELTIF redemption policy: notice periods, LMTs and the redemption cap
An ELTIF may offer redemptions during its life only under Article 18(2) of Regulation (EU) 2015/760. Delegated Regulation (EU) 2024/2759 sets the policy content, optional anti-dilution tools and the maximum redemption percentage, calibrated on frequency and notice period or on a liquid-asset floor.
ELTIF RTS: what Delegated Regulation (EU) 2024/2759 covers
Delegated Regulation (EU) 2024/2759 is the level 2 measure for ELTIF 2.0. Its 13 articles and two annexes cover hedging, fund life versus asset life-cycles, the minimum holding period, redemption policy and liquidity tools, the redemption cap, matching, disposal of assets and cost disclosure.
ELTIF vs LTAF vs RAIF vs UCI Part II: a structural comparison
ELTIF is an EU product label with a retail passport. LTAF is a UK authorised open-ended fund under FCA rules. RAIF and UCI Part II are Luxembourg fund regimes; a RAIF is reserved to well-informed investors and is not supervised by the CSSF, a Part II UCI needs CSSF authorisation. A RAIF or Part II UCI can also be authorised as an ELTIF.
Semi-liquid and evergreen funds: how open-ended ELTIFs work
Semi-liquid or evergreen funds hold illiquid private assets but accept new money and offer limited, periodic redemptions. ELTIF 2.0 makes this possible for ELTIFs through Article 18(2), with a minimum holding period, a redemption cap linked to liquid assets and pro rata reduction. The core risk is a liquidity mismatch.
How do funds value properties? Methods, valuers and NAV
Real-estate funds value their buildings through independent valuers who estimate market value with the income, comparison or cost approach. A valuation is an informed estimate, not a sale price, it is updated at intervals set by the fund rules, and the NAV can therefore lag the market.
Diversification in a real-estate fund: what it covers and its limits
A real-estate fund diversifies by spreading money across sectors, locations, tenants, lease expiries and property sizes. An ELTIF may hold at most 20 % of its capital in a single real asset. Diversification reduces the impact of one problem but cannot remove market, interest rate or liquidity risk.
What are the risks of a real-estate fund? A practical guide
A real-estate fund can lose value. Its main risks are valuation, vacancy, tenant default, interest rates and refinancing, leverage, limited liquidity, concentration, development, currency and costs. Each one shows up in specific parts of the fund documents.
Real-estate fund vs buying a flat to let: how they compare
A real-estate fund offers pooled, managed exposure with less hands-on work, while a rental flat gives direct control but concentrates capital, effort and risk in one asset. Neither is better in general: it depends on your goal, horizon and need for liquidity.
Rental yield explained: gross vs net and why it is not fund return
Rental yield is annual rent divided by the value of a property. Gross yield uses total rent; net yield deducts costs the owner cannot recover from tenants. Neither equals the return of a real estate fund, which also depends on fund costs, changes in property values and borrowing.
Retail parks as an investment: how they work and what to check
A retail park is a group of large retail units around a shared car park, usually at the edge of a town. Its income comes from leases with retailers, and it depends on visitor numbers, the mix of tenants and lease terms. Key risks are online competition, dependence on a few tenants and vacancy.