Offices
Rental income depends on occupancy and the length of leases.
Independent explanations of European long-term investment funds and real estate investing. No promised returns, primary sources throughout.
Informational content. Not investment advice and not an offer.
Illustrative photographs. They do not show properties of any fund. Photos: Pexels.
Guides, comparisons and explainers built on primary sources.
An ELTIF is a European fund label for long-term investment in real assets and unlisted businesses. It follows EU rules, must be run by an authorised AIFM, can be offered to retail investors after a suitability assessment, and is not a daily-liquid product.
ELTIF 2.0 is Regulation (EU) 2023/606, which amended the ELTIF Regulation and applies from 10 January 2024. It widened eligible assets, raised borrowing limits, removed retail entry barriers and set conditions for redemptions during the life. The long-term, illiquid nature of ELTIFs did not change.
A neutral comparison of ELTIFs, UCITS funds, ETFs, open-ended real-estate AIFs, funds for professional or qualified investors and direct property: how each is regulated, who it is for, how liquid it is, what it holds and what to watch out for.
ELTIF investors can lose part or all of their capital, may be unable to sell when they wish, and depend on estimated valuations. Borrowing, concentration, costs, interest rates, tenants and currency add risks that vary by fund and are not removed by the ELTIF label.
ELTIF 2.0 article by article: RTS, redemptions, matching, leverage, portfolio rules and structures.
Regulation (EU) 2023/606 amended the ELTIF Regulation from 10 January 2024. It widened eligible assets, lowered the eligible-asset floor to 55 %, moved borrowing to a NAV basis, created a professional-only regime, opened redemptions and matching, and grandfathered existing ELTIFs until 11 January 2029.
Under Article 16 of the ELTIF Regulation, an ELTIF that can be marketed to retail investors may borrow cash up to 50 % of NAV, and a professional-only ELTIF up to 100 % of NAV. Borrowing must serve investment or liquidity, match the asset currency or be hedged, and not outlast the fund.
Of 327 ELTIFs in the ESMA register as of 31 August 2026, 176 are domiciled in Luxembourg, 87 in France and 35 in Ireland. Luxembourg offers several fund wrappers and exempts ELTIFs from subscription tax; Ireland has a dedicated ELTIF chapter in its AIF Rulebook and the ICAV structure.
An ELTIF must be authorised before it is marketed, and the authorisation is valid in all Member States. Marketing uses the AIFMD notification procedure for professional and retail investors. Retail sales require a MiFID II suitability assessment, a suitability statement and written alerts.
ELTIF 2.0 allows an ELTIF to invest in other ELTIFs, EuVECAs, EuSEFs, UCITS and EU AIFs, and creates a formal master-feeder regime in which a feeder ELTIF invests at least 85 % of its assets in a master ELTIF, with look-through for the portfolio limits.
Article 19(2a) of the ELTIF Regulation lets fund rules provide for matching transfer requests of exiting investors with those of new investors during the life. It requires a written matching policy, fair and pro rata treatment and compatibility with liquidity management; the RTS adds pricing, timing and disclosure rules.
An ELTIF must invest at least 55 % of capital in eligible investment assets under Articles 10 and 11. Retail-eligible ELTIFs face 20 % single-asset limits and concentration caps; professional-only ELTIFs are exempt from most. The rules apply from a ramp-up date of at most five years or half the life.
An ELTIF needs a published prospectus before any marketing and a PRIIPs key information document before marketing to retail investors. The prospectus has ELTIF-specific contents and cost disclosure, and the annual report adds items to the AIFMD annual report, due within six months of year end.
An ELTIF may offer redemptions during its life only under Article 18(2) of Regulation (EU) 2015/760. Delegated Regulation (EU) 2024/2759 sets the policy content, optional anti-dilution tools and the maximum redemption percentage, calibrated on frequency and notice period or on a liquid-asset floor.
Five guides that cover the basics before any decision.
Three kinds of commercial property that real estate funds hold most often.
Illustrative photographs. They do not show properties of any fund. Photos: Pexels.
Real estate investing Rental income depends on occupancy and the length of leases.
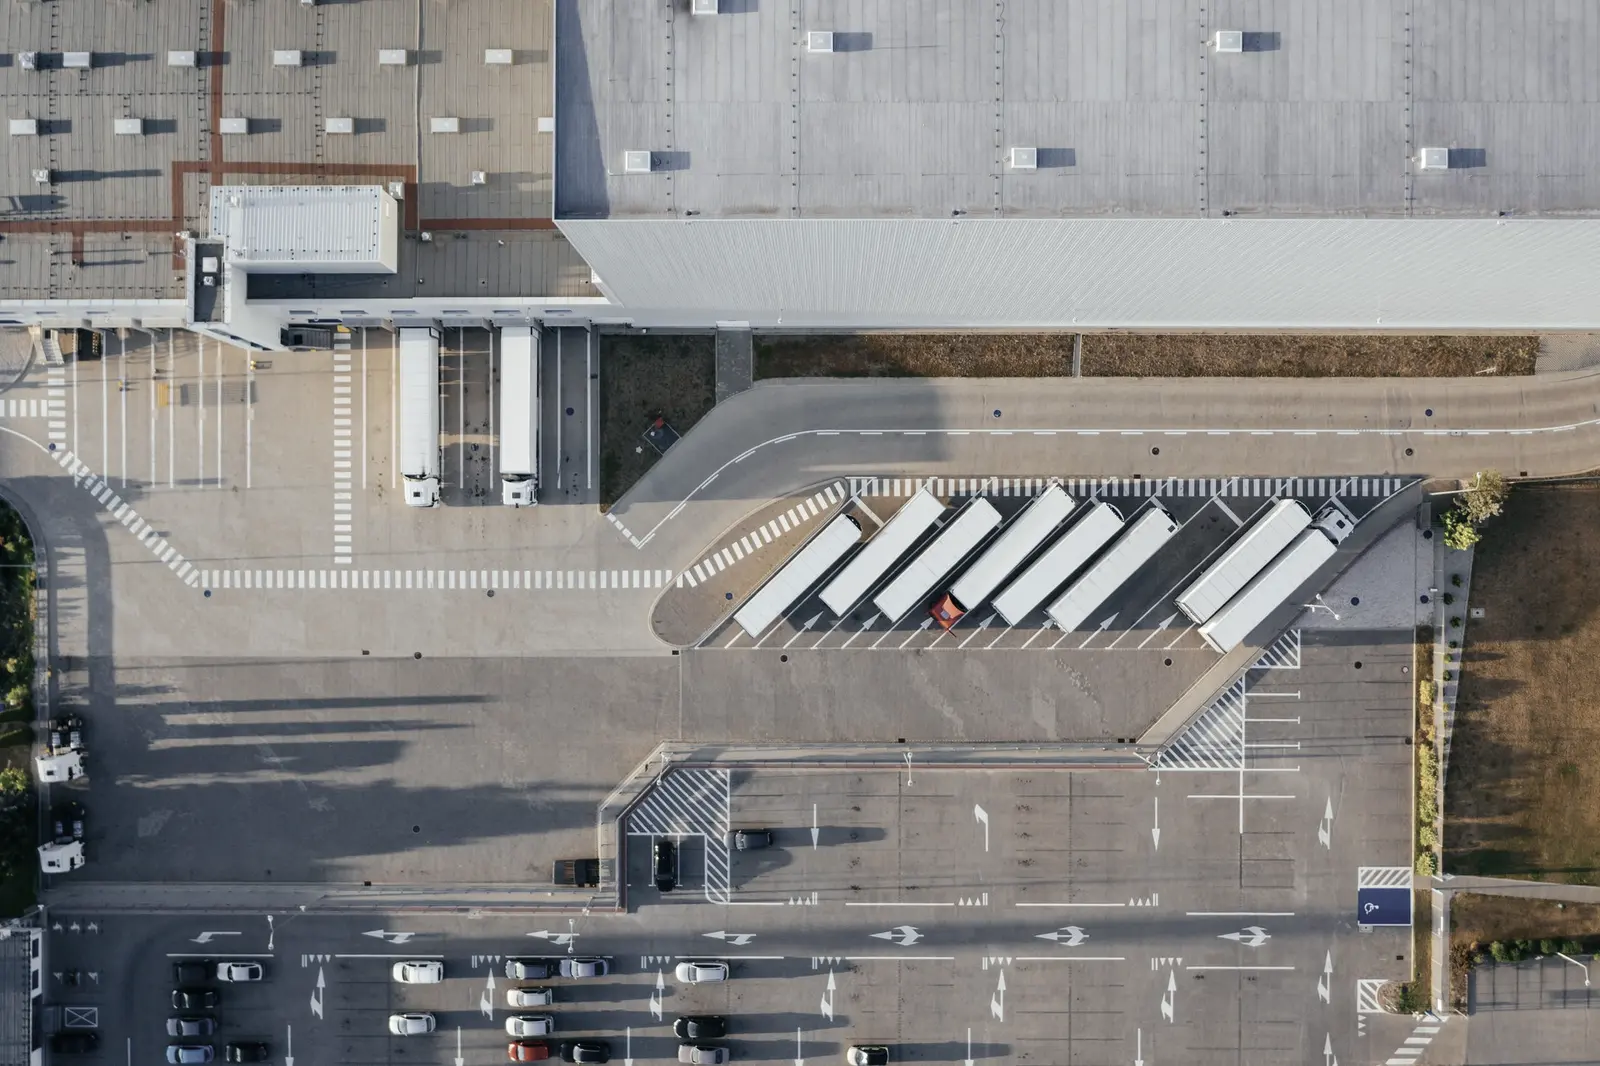
Warehouses and distribution centres. Returns depend on tenants and location.
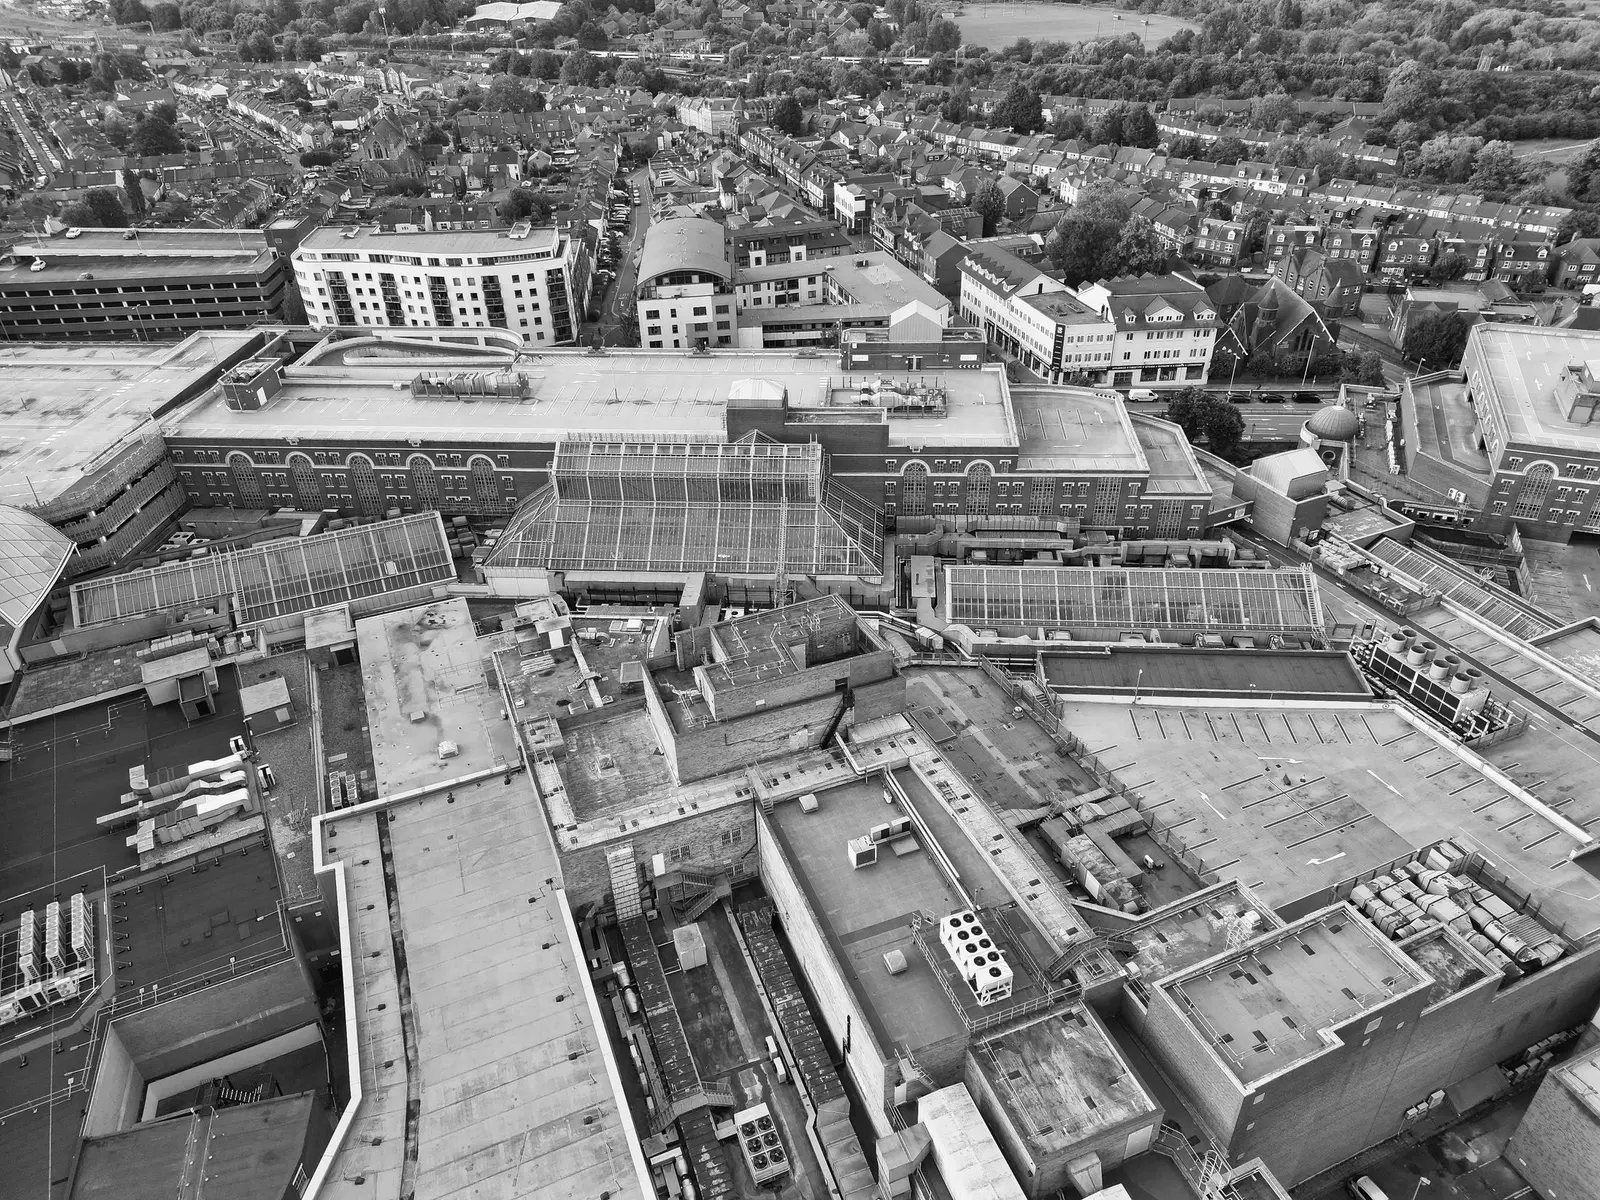
Retail space on the edge of cities. Returns depend on tenants and footfall.
Compares investment value at the same gross return with and without fees.
The result is not a return forecast for any fund nor a suitability assessment. You enter the return; model values are illustration only.
Every claim about a fund rests on a dated primary source. We do not publish unverified figures.
Claims rest on EU legislation on EUR-Lex and ESMA material. Every article lists its sources.
Financial figures show their source, date and what they apply to. We do not use unsourced figures.
We check facts against the text of the legislation, show each article’s review status and update texts regularly.